 लेखक:
संक्षेप में: CIBIL score आपका loan repayment history संक्षेप में दिखाता है। अच्छा score कैसे बनता है और किन गलतियों से नुकसान हो सकता है, समझिए।
CIBIL Score क्या बताता है
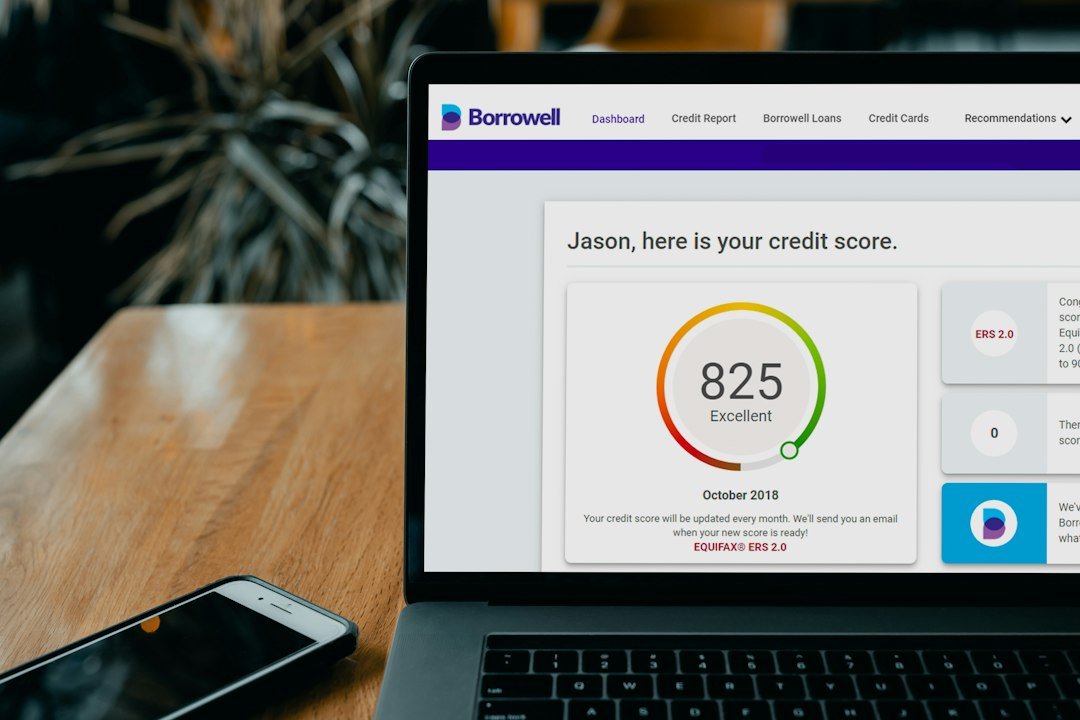
भारत में CIBIL Score credit behavior का तीन अंकों का summary indicator है, जिसकी बताई गई range 300 से 900 तक होती है। यह lenders को आपकी borrowing और repayment history से जुड़ी information समझने में सहायता करता है। लेकिन score किसी future loan approval की guarantee नहीं है। Bank income, employment, existing obligations, product rules और अपनी underwriting policy भी देख सकता है। इसलिए ‘750 पार, loan पक्का’ जैसी lines को absolute rule न समझें।
Credit Report और Score में फर्क
Credit report में loan accounts, repayment history, outstanding balances तथा enquiry details जैसी जानकारी हो सकती है। Score उसी data और scoring model के आधार पर बनाया गया numeric summary है। केवल number देखने से किसी error या unauthorized account का पता नहीं चलेगा। इसलिए report पढ़ना बहुत उपयोगी है। Credit information ब्यूरो के पास lenders द्वारा दी गई जानकारी के आधार पर आती है; उसे बदलने का निर्धारित dispute process होता है।
Payment history सबसे महत्वपूर्ण आदत
EMI, credit-card due और अन्य obligations समय पर चुकाना responsible credit record बनाए रखने का बुनियादी कदम है। Late payments अलग-अलग severity के साथ report में आ सकते हैं और score को प्रभावित कर सकते हैं। Payment करने के बाद receipt तथा bank posting confirm करें, खासकर due date के आसपास। Technical delay और genuine default की स्थिति में lender से स्पष्ट documentation लें। केवल auto-debit लगा देना प्रत्येक महीने sufficient balance रखने की जिम्मेदारी समाप्त नहीं करता।
Credit utilization क्या है
Credit utilization मोटे तौर पर उपलब्ध credit limit के मुकाबले इस्तेमाल की गई credit राशि का अनुपात है। मान लें card limit ₹1,00,000 है और outstanding ₹70,000, तो utilization काफी ऊँचा है। लगातार बहुत अधिक outstanding credit risk का signal बन सकता है। हालांकि ‘सिर्फ 30 प्रतिशत से नीचे रहना ही एकमात्र नियम है’ जैसा दावा हर scoring model पर लागू नहीं होगा। अपनी spending और repayment affordability को प्राथमिकता दें।
Multiple loan enquiries का असर
नए credit cards और loans के लिए बार-बार आवेदन करने पर lenders credit enquiries दर्ज कर सकते हैं। कम समय में कई applications risk perception को प्रभावित कर सकती हैं। लेकिन अपनी report स्वयं check करने और lender के formal application enquiry में अंतर होता है। किसी app के ‘preapproved’ label को actual sanction न मानें; application terms जाँचें। आवश्यकता के बिना कई lenders के पास simultaneously apply करने से बचना समझदारी है।
Credit history की उम्र और mix
पुराने accounts पर समय के साथ reliable repayments का record बने तो यह credit profile में सहायक हो सकता है। Secured और unsecured borrowing का संयोजन भी scoring factors में शामिल हो सकता है। इसका मतलब score बढ़ाने के लिए अनावश्यक loan लेना नहीं है। हर नया debt interest और repayment risk जोड़ता है। सही goal financially responsible behavior होना चाहिए, किसी scoring formula को कृत्रिम ढंग से manipulate करना नहीं।
Report में गलती कैसे सुधारें
अगर आपके नाम पर unfamiliar loan, गलत late-payment record या duplicate account दिखाई दे तो पहले lender और credit bureau के official dispute mechanism का उपयोग करें। Account details, evidence और complaint reference संभालें। Report updates में समय लग सकता है; हर dispute तुरंत आपके पक्ष में resolve होगा, इसकी guarantee नहीं। Fraud का संदेह होने पर bank के security channel और जरूरत पड़ने पर cybercrime reporting भी करें।
Score कितनी बार जाँचना चाहिए
अपनी credit report regular अंतराल पर देखना उपयोगी हो सकता है, विशेषकर नए loan application से पहले या unexpected alert मिलने पर। Official CIBIL channel से report access के नियम तथा उपलब्ध free annual report जैसी सुविधाओं की current conditions देखें। Third-party apps को अनावश्यक permissions देने से बचें। केवल score alert देखकर panic में multiple credit products बंद न करें; पहले underlying information समझें।
Business owner के लिए महत्व
छोटे व्यवसाय चलाने वाले founders अक्सर personal credit और business credit को अलग रखने में कठिनाई महसूस करते हैं। Personal loan account, business borrowing, co-signed obligations और cash flow को स्पष्ट रखें। Corporate credit assessment और individual CIBIL Score अलग products और parameters हो सकते हैं। बैंक के loan officer के साथ आवेदन की specific eligibility और documentation पहले समझें। Repo rate और lending terms भी अलग विषय हैं।
सात काम जिनसे profile सुधर सकती है
हर due समय से भरें; utilization को नियंत्रित रखें; अनावश्यक applications कम करें; report errors dispute करें; joint या guaranteed loans पर नजर रखें; repayment receipts संभालें; और budget के अनुसार debt लें। किसी company के पैसे लेकर ‘score तुरंत 900 कर देंगे’ जैसे दावे पर विश्वास न करें। Credit profile समय के साथ वास्तविक व्यवहार को reflect करती है; instant hacks भरोसेमंद नहीं।
निष्कर्ष
CIBIL Score को अपनी credit discipline का एक संकेत समझें, संपूर्ण financial health का माप नहीं। भरोसेमंद repayment, सही report और नियंत्रित उधारी लंबे समय में मदद कर सकती है। Loan approval या interest rate का अंतिम निर्णय lender करता है। यह सामान्य शिक्षा है, व्यक्तिगत loan approval prediction नहीं।
अक्सर पूछे जाने वाले सवाल
CIBIL Score कितने से कितने तक होता है?
CIBIL के अनुसार 300 से 900 तक।
क्या ऊँचा score होने पर loan guaranteed है?
नहीं। Lender दूसरी eligibility शर्तें भी जाँचता है।
क्या अपना CIBIL Score खुद देखने से score घटता है?
Official self-check और lender hard enquiry की प्रकृति अलग हो सकती है; current terms देखें।
क्या FD होने से score अपने-आप बढ़ेगा?
Credit score loan repayment information पर आधारित होता है; FD balance अकेला equivalent नहीं है।
Report गलत हो तो क्या करें?
Credit bureau और reporting lender के official dispute channels अपनाएँ।
संबंधित लेख
संदर्भ
Sources reviewed: 11 अक्टूबर 2026। यह सामान्य educational information है; वित्तीय निर्णय से पहले current official terms देखें।
इस विषय पर आगे क्या पढ़ें?
इस खबर से जुड़े विषयों को आसान भाषा में और गहराई से समझें।